Navigating 2026 Interest Rate Hikes: Investment Strategies for a 4.5% Fed Funds Rate
Anúncios
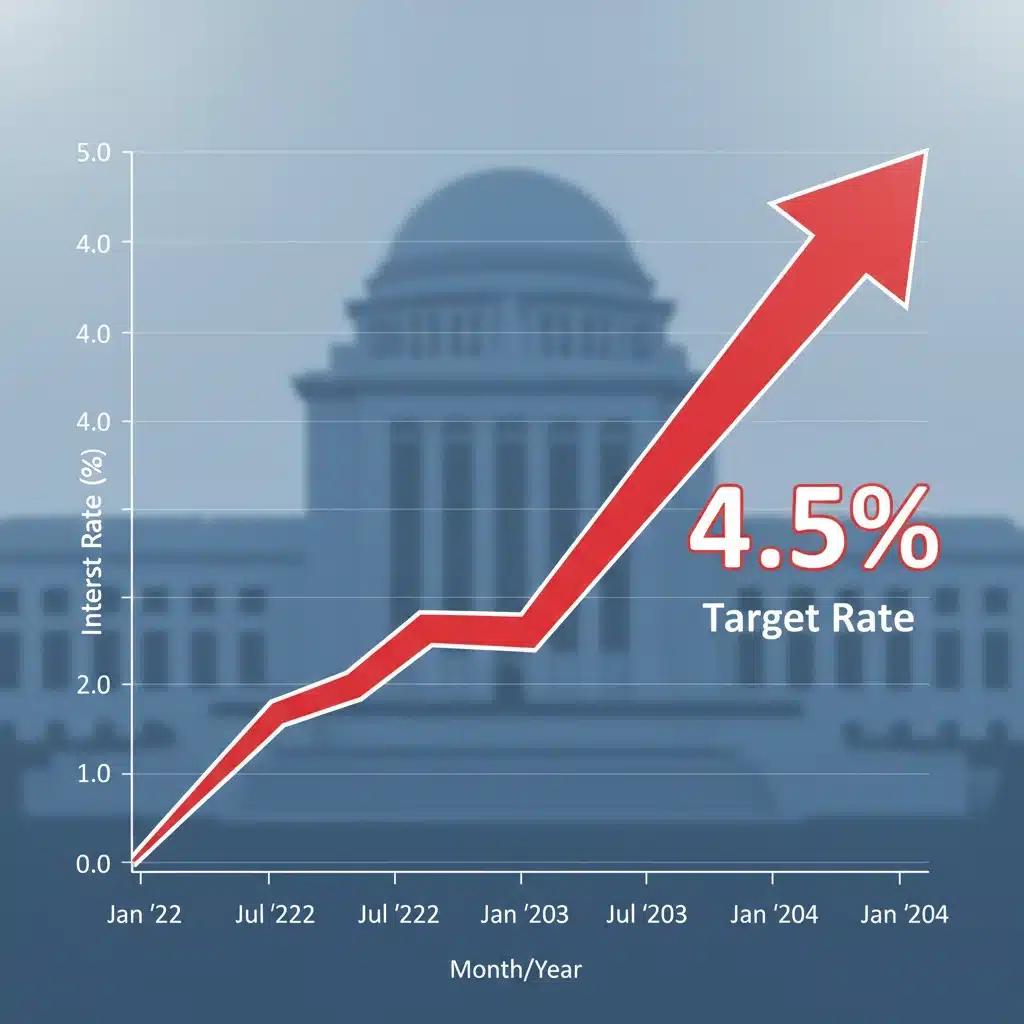
The financial world is perpetually in motion, and as we look towards 2026, one of the most significant anticipated shifts is the potential for a substantial increase in interest rates, with projections indicating a Federal Funds Rate potentially reaching 4.5%. This shift, driven by a complex interplay of inflation, economic growth, and monetary policy, has profound implications for investors across all asset classes. Understanding these dynamics and implementing proactive 2026 interest rate strategies will be paramount for safeguarding and growing wealth.
For years, investors have enjoyed an era of historically low-interest rates, a period that fueled robust growth in equities and real estate, and made borrowing relatively inexpensive. However, as central banks around the globe grapple with persistent inflationary pressures and seek to normalize monetary policy, the tide is turning. A 4.5% Fed Funds Rate by 2026 would represent a significant pivot, impacting everything from consumer lending rates to corporate borrowing costs, and ultimately, the valuation of investments.
Anúncios
This comprehensive guide will delve into the anticipated economic landscape of 2026, analyze the potential impact of higher interest rates on various investment vehicles, and, most importantly, outline actionable 2026 interest rate strategies that investors can adopt to navigate this evolving environment successfully. From re-evaluating fixed-income portfolios to identifying resilient equity sectors and exploring alternative investments, we will provide a roadmap for financial resilience and opportunistic growth.
Understanding the Economic Context: Why a 4.5% Fed Funds Rate?
Before diving into specific investment strategies, it’s crucial to understand the rationale behind the projected 4.5% Fed Funds Rate. Several macroeconomic factors contribute to this outlook:
Persistent Inflationary Pressures
The post-pandemic economic recovery has been characterized by elevated inflation, fueled by supply chain disruptions, strong consumer demand, and geopolitical events. While some inflationary pressures may abate, underlying factors such as wage growth and de-globalization trends could keep inflation above central banks’ target levels. To combat this, the Federal Reserve utilizes interest rate hikes as a primary tool to cool the economy and bring inflation back under control.
Anúncios
Robust Economic Growth and Labor Market
Despite concerns about a potential recession, many economists project continued, albeit perhaps slower, economic growth into 2026. A strong labor market, characterized by low unemployment and rising wages, can contribute to sustained consumer spending and inflationary pressures. In such an environment, the Fed might feel compelled to maintain a tighter monetary policy to prevent the economy from overheating.
Normalization of Monetary Policy
The period of ultra-low interest rates was largely a response to the 2008 financial crisis and the COVID-19 pandemic. As economies stabilize and grow, central banks aim to normalize monetary policy, bringing interest rates to a level that is neither excessively stimulative nor restrictive. A 4.5% Fed Funds Rate could be seen as a more neutral stance in a healthy, growing economy, allowing the Fed flexibility to respond to future economic shocks.
Global Economic Interdependencies
The U.S. economy does not operate in isolation. Global economic conditions, including inflation rates in other major economies, central bank actions abroad, and geopolitical stability, all play a role in shaping the Fed’s decisions. A synchronized global effort to combat inflation could reinforce the need for higher rates in the U.S.
Impact of Higher Interest Rates on Investment Portfolios
A 4.5% Fed Funds Rate will send ripples across all investment landscapes. Understanding these impacts is the first step in formulating effective 2026 interest rate strategies.
Fixed Income: A Double-Edged Sword
Rising interest rates generally have an inverse relationship with bond prices. As new bonds are issued with higher yields, older, lower-yielding bonds become less attractive, causing their market value to fall. However, for investors with a long-term horizon, higher rates also mean higher potential income from newly issued bonds and bond funds as they reinvest at more favorable yields.
- Existing Bonds: Investors holding long-duration bonds will likely see principal depreciation.
- New Bonds: Higher yields will make new bond issues more appealing, offering better income opportunities.
- Bond Funds: Actively managed bond funds with shorter durations or those focused on floating-rate securities may perform better.
Equities: Sectoral Divergence
The impact on the stock market is more nuanced. Higher interest rates increase borrowing costs for companies, which can compress profit margins, especially for highly leveraged businesses. They also make future earnings less valuable in present-day terms (discounting effect). However, not all sectors are equally affected:
- Growth Stocks: Often more sensitive to interest rate hikes due to their reliance on future earnings growth and higher debt levels for expansion.
- Value Stocks: May be more resilient, particularly those with strong balance sheets, consistent cash flows, and less reliance on future growth projections.
- Financials: Banks and other financial institutions can sometimes benefit from higher net interest margins (the difference between what they pay on deposits and earn on loans).
- Utilities and Real Estate Investment Trusts (REITs): These sectors, often seen as bond proxies due to their dividend yields, can face headwinds as higher interest rates make bonds more competitive.
Real Estate: Cooling Market
Higher mortgage rates directly impact housing affordability, potentially cooling down red-hot real estate markets. Commercial real estate can also be affected as borrowing costs for development and acquisitions rise, and capitalization rates adjust upwards. However, certain segments, like industrial properties or those with long-term leases and built-in rent escalators, might show more resilience.
Commodities: Mixed Signals
The impact on commodities is complex. A stronger dollar, often a consequence of higher interest rates, can make dollar-denominates commodities more expensive for international buyers, potentially dampening demand. However, if inflation remains a concern, some commodities, particularly precious metals like gold, might serve as a hedge against currency devaluation.
Proactive 2026 Interest Rate Strategies for Investors
Given the anticipated economic shifts, adopting specific 2026 interest rate strategies is crucial. Here are key approaches to consider for your portfolio:
1. Re-evaluate Your Fixed Income Portfolio
For bond investors, duration management becomes paramount. Duration measures a bond’s sensitivity to interest rate changes. In a rising rate environment, shorter-duration bonds are preferable as their prices are less volatile. Consider:
- Short-Duration Bonds and Funds: Shift towards bonds or bond funds with shorter maturities (e.g., 1-5 years).
- Floating-Rate Notes: These bonds have interest payments that adjust periodically based on a benchmark rate, offering protection against rising rates.
- Treasury Inflation-Protected Securities (TIPS): While their principal value is adjusted for inflation, their yields might still be affected by rising nominal rates. However, they offer a hedge against persistent inflation.
- Laddering Strategy: Invest in bonds with staggered maturity dates. As shorter-term bonds mature, you can reinvest the proceeds into new, higher-yielding bonds.
2. Optimize Your Equity Exposure
The stock market will likely see a rotation. Focus on sectors and companies that can thrive or remain resilient in a higher interest rate environment:
- Value Stocks: Companies with strong balance sheets, stable earnings, and attractive valuations tend to outperform growth stocks during periods of rising rates. Look for established companies with a history of profitability and dividend payments.
- Financial Sector: Banks, insurance companies, and brokerage firms can often benefit from higher net interest margins as rates rise.
- Healthcare: Generally considered a defensive sector, healthcare demand is less cyclical. Companies with strong pricing power and essential services can be good hedges.
- Consumer Staples: Companies that produce everyday necessities tend to be more resilient during economic shifts, as demand remains relatively stable regardless of interest rates.
- Companies with Pricing Power: Businesses that can pass on higher costs (including borrowing costs) to consumers without significantly impacting demand are well-positioned.
- Avoid Highly Leveraged Companies: Scrutinize companies with heavy debt loads, as their interest expenses will increase, eating into profits.
3. Re-evaluate Real Estate Holdings and Opportunities
While higher rates can cool the broader real estate market, specific strategies can still yield returns:
- Commercial Real Estate with Strong Leases: Focus on properties with long-term leases and reliable tenants, especially those with rent escalators tied to inflation. Industrial and logistics properties may continue to perform well due to e-commerce growth.
- Debt Reduction: For existing property owners, consider accelerating mortgage payments or refinancing into fixed-rate loans if current rates are still favorable compared to future projections.
- Real Estate Debt Funds: These funds invest in mortgage-backed securities or provide loans for real estate projects, potentially offering attractive yields in a higher rate environment.
4. Consider Alternative Investments
Diversifying into alternative assets can provide uncorrelated returns and act as a hedge against traditional market volatility:
- Private Credit: Direct lending to businesses can offer higher yields than traditional bonds, often with floating rates that benefit from rising interest rates.
- Infrastructure: Investments in essential infrastructure projects (e.g., utilities, transportation) can provide stable, inflation-linked revenues.
- Managed Futures: These strategies can profit from both rising and falling markets by taking long and short positions across various asset classes.
- Commodities: While nuanced, certain commodities can still serve as an inflation hedge. Gold, in particular, often performs well during periods of economic uncertainty and inflation.
5. Manage Your Own Debt
Higher interest rates will make borrowing more expensive. Proactive debt management is a crucial personal finance strategy:
- Pay Down High-Interest Debt: Prioritize credit card debt, personal loans, and other variable-rate loans before rates climb further.
- Refinance Mortgages: If you have a variable-rate mortgage, consider refinancing into a fixed-rate loan while rates are still manageable.
- Avoid Unnecessary New Debt: Be more discerning about taking on new loans, as the cost of borrowing will be significantly higher.
6. Emphasize Cash Flow and Dividend Income
In an environment where capital appreciation might be more challenging, focus on investments that generate consistent income:
- Dividend Growth Stocks: Companies with a history of increasing their dividends can provide a growing income stream and often demonstrate financial stability.
- High-Yield Savings Accounts and CDs: As interest rates rise, these options become more attractive for parking cash and earning a respectable, low-risk return.
7. Review Your Financial Plan and Risk Tolerance
A rising interest rate environment necessitates a thorough review of your overall financial plan. Your risk tolerance might change as market conditions become more volatile. Engage with a financial advisor to:
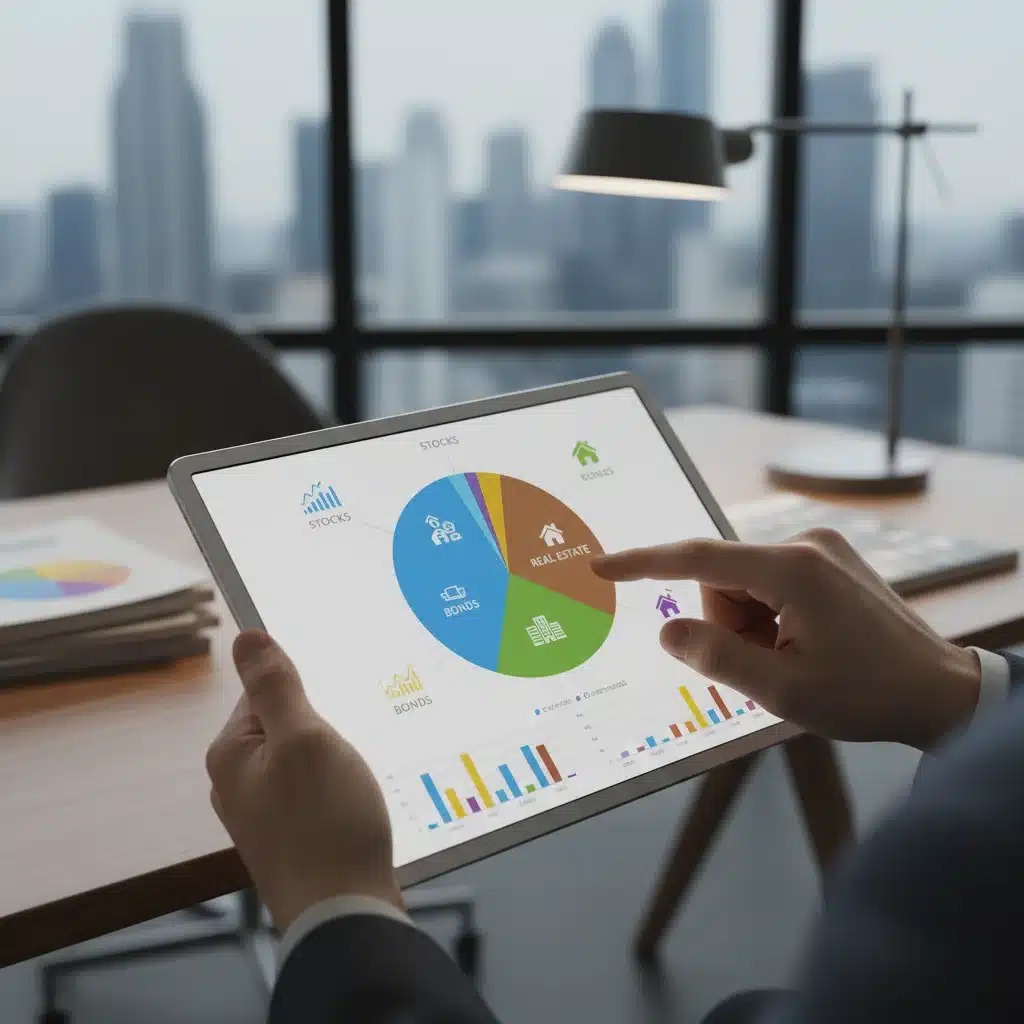
- Assess Your Asset Allocation: Ensure your portfolio is appropriately diversified and aligned with your long-term goals and risk profile in the new rate environment.
- Stress Test Your Portfolio: Understand how your investments might perform under various interest rate scenarios.
- Adjust Goals: Be realistic about potential returns and adjust your financial goals accordingly.
Potential Pitfalls and How to Avoid Them
While opportunities exist, several pitfalls can ensnare unprepared investors:
- Panic Selling: Reacting emotionally to market volatility can lead to selling assets at a loss. Maintain a long-term perspective.
- Ignoring Inflation: While rates are rising to combat inflation, inflation itself erodes purchasing power. Ensure your investments offer some level of inflation protection.
- Over-Concentration: Relying too heavily on one asset class or sector can expose you to undue risk. Diversification remains key.
- Chasing Yield: Be wary of investments offering unusually high yields, as they often come with significantly higher risk.
The Role of the Federal Reserve and Market Communication
The Federal Reserve’s communication will be critical in shaping market expectations. Investors should closely monitor:
- FOMC Statements: The Federal Open Market Committee’s decisions and forward guidance on interest rates.
- Economic Projections: The Fed’s forecasts for inflation, unemployment, and GDP growth.
- Speeches by Fed Officials: Insights from individual governors can provide clues about future policy direction.
Transparent communication from the Fed can help stabilize markets and allow investors to adjust their 2026 interest rate strategies more effectively. However, unexpected shifts or ambiguous statements can lead to increased volatility.
Conclusion: Adapting to a New Financial Paradigm
The prospect of a 4.5% Fed Funds Rate by 2026 marks a significant shift from the low-interest-rate environment that has prevailed for much of the past decade. This change is not merely a technical adjustment; it represents a fundamental re-pricing of risk and capital across the global economy. For investors, this new paradigm demands a proactive and adaptable approach.
Implementing sound 2026 interest rate strategies involves a careful re-evaluation of existing portfolios, a shift towards more resilient asset classes, and a keen eye on income generation and debt management. By focusing on shorter-duration fixed income, value-oriented equities, strategic real estate plays, and diversifying into appropriate alternative investments, individuals can not only protect their wealth but also identify new avenues for growth.
Remember, financial planning is an ongoing process. Regular reviews of your portfolio, staying informed about macroeconomic trends, and consulting with financial professionals will be invaluable as you navigate the complexities of a rising interest rate environment. The future belongs to those who are prepared to adapt and innovate, transforming potential challenges into strategic opportunities.