Demystifying Financial Benefits: A Beginner’s Playbook for Maximizing Your Resources
Anúncios
Navigating the world of finance often feels like trying to read a map in a foreign language. Terms like ‘tax-advantaged accounts,’ ‘federal grants,’ and ‘public assistance’ are thrown around, but few people understand the immense value hidden behind the jargon. The common assumption is that these benefits are only for dire emergencies or for a select few. This belief costs the average person thousands of dollars in unclaimed funds over their lifetime—money they are fully entitled to but leave on the table due to complexity or a simple lack of awareness.
This is not about finding loopholes; it’s about using a system that was designed, in part, to support you. Financial benefits are a diverse ecosystem of tools intended to foster stability and growth. From funding higher education and encouraging retirement savings to providing a key safety net during unexpected hardship, these programs are woven into the fabric of the economy. You have likely already paid into many of them through your taxes. The challenge isn’t a lack of resources, but a lack of a clear, straightforward guide to accessing them.
Anúncios
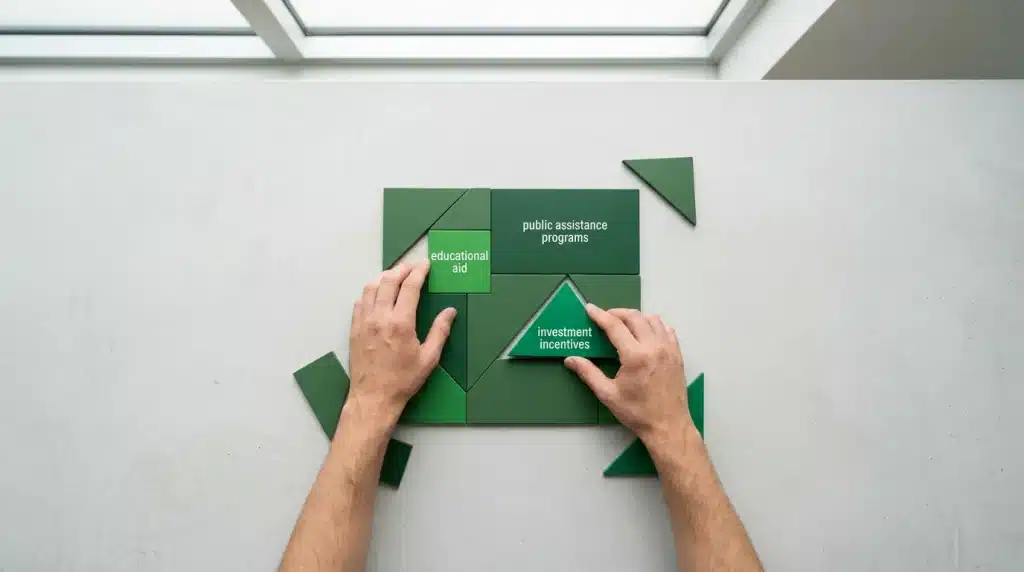
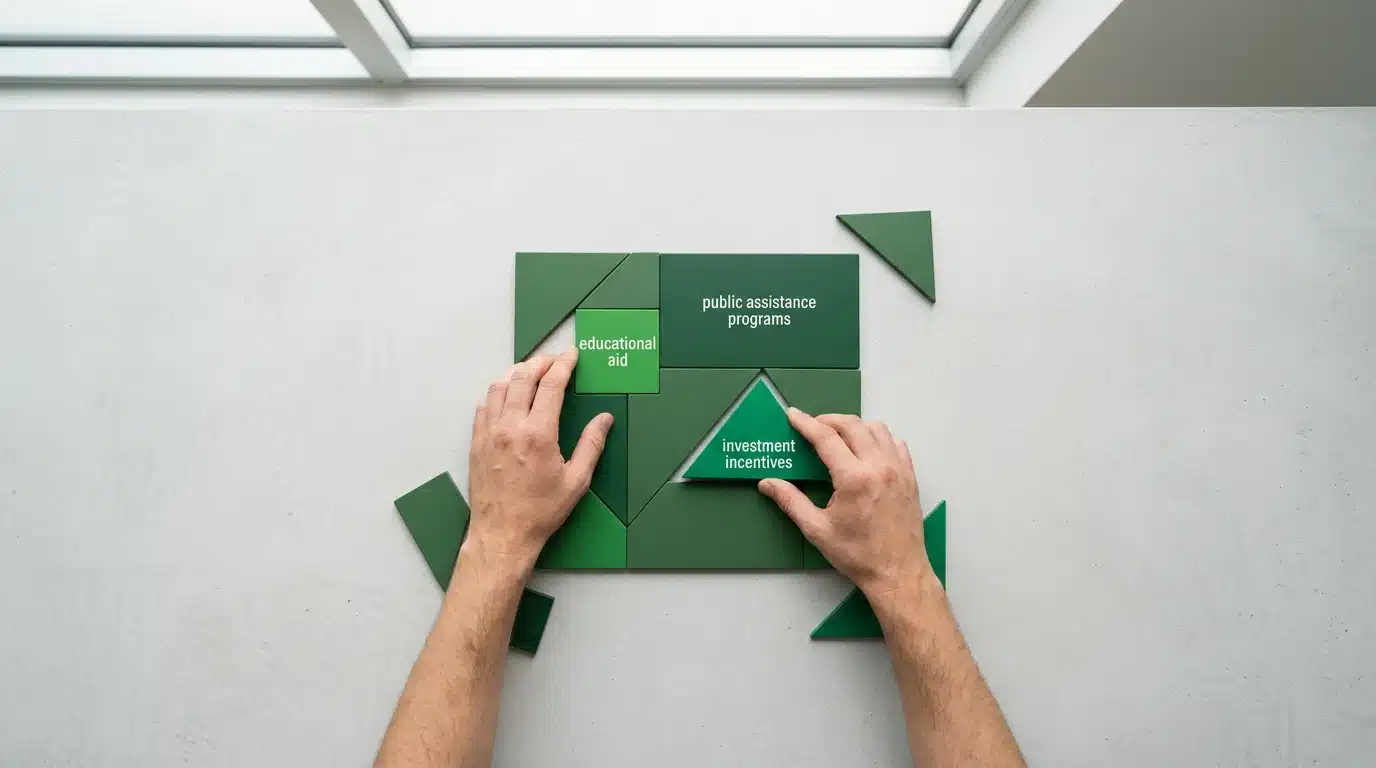
So, where does one begin? This playbook demystifies the entire landscape. We will break down the three core pillars of financial support: educational benefits that make learning affordable, investment incentives that accelerate wealth creation, and public assistance frameworks that provide stability when you need it most. By the end, you’ll have a practical strategy to move from being a passive observer to an active participant in your own financial well-being, equipped to claim the resources waiting for you.
Understanding the Landscape of Financial Assistance
Most people believe they understand financial assistance, assuming it’s a monolithic system for the destitute. They are almost always wrong. The reality is a complex ecosystem of distinct support structures, each designed for a specific purpose. Think of it less as a single safety net and more as a series of specialized tools—some for immediate need, others for future growth. The three primary categories are public assistance from government programs, aid specifically for navigating the educational landscape, and incentives designed to encourage smart financial decisions.
The sheer volume of available support is staggering, yet a significant portion remains untouched. According to a report from the Urban Institute, an estimated 18% of families eligible for key nutritional benefits fail to apply, often due to a lack of awareness or perceived complexity. This highlights a critical disconnect in how people approach the entire system of modern public assistance and its evolving frameworks.
Anúncios
Leaving free money on the table is a choice.
What most people miss is how these categories can interact. Public benefits might free up income that can then be directed toward tax-advantaged retirement accounts—a form of investment incentive. Similarly, educational grants reduce the debt burden, which directly impacts long-term financial health and the capacity for strategic asset allocation later in life. Ignoring one category because you believe you only qualify for another is like a carpenter refusing to use a hammer because they own a screwdriver.
The initial challenge isn’t eligibility; it’s awareness. Understanding which doors are even available to knock on is the first, and most critical, step in taking control of your financial well-being.
Navigating Educational Benefits: Funding Your Learning Journey
Most people believe higher education is an insurmountable financial mountain. They are wrong. The reality is that billions in educational funding are left unclaimed every year simply because potential applicants are paralyzed by complexity or ignorance of what’s available. This isn’t just about student loans; it’s about free money waiting for a home.
The Department of Education reports that a staggering amount in federal grants goes unused annually, with one recent analysis showing over $2.6 billion in Pell Grants unclaimed by eligible students. The system is intentionally complicated. Navigating it requires a strategy, not just hope.
Types of Educational Funding: Grants, Scholarships, and Loans
Understanding the core differences between funding types is the first critical step. Think of it like building a financial toolkit; you wouldn’t use a hammer to turn a screw. Each tool has a specific purpose, and mixing them up can be a costly mistake.
The primary categories are quite distinct:
- Grants: This is need-based gift aid that you do not have to repay. Federal Pell Grants and state-specific grants fall into this category, forming the foundation of many aid packages.
- Scholarships: These are merit-based awards, often provided by private organizations, universities, or foundations. They can be based on academic achievement, athletic skill, or specific talents. Unlike grants, they are competitive.
- Loans: This is borrowed money that must be repaid with interest. Federal loans (like Stafford or Perkins loans) typically offer better terms and more flexible repayment options than private loans from banks. This should always be the last resort.
The underrated factor here is the power of stacking. Combining a federal grant with a local scholarship can significantly reduce the need for any loans, a core principle in maximizing your overall benefits and securing your financial future.
Primary Steps for Applying for Student Aid
The application process can feel like assembling furniture with vague instructions. But where does one even begin with this alphabet soup of acronyms? There is a clear, repeatable sequence that cuts through the noise.
Start with a methodical approach. It pays off.
Follow these initial steps to get organized and begin the process — and yes, that includes the often-dreaded FAFSA (Free Application for Federal Student Aid).
- Create a Federal Student Aid (FSA) ID: Before anything else, both the student and at least one parent (for dependent students) need to create an FSA ID. This acts as your legal electronic signature for all federal aid documents.
- Gather Your Documents: You will need Social Security numbers, federal income tax returns, W-2s, and records of untaxed income. Having these on hand before you start prevents major headaches. According to financial aid advisor Dr. Elena Vance, “The single biggest delay is students scrambling for documents mid-application.”
- Complete the FAFSA: Fill out the FAFSA as soon as it becomes available. Aid from many sources is distributed on a first-come, first-served basis, so timeliness is critical for anyone serious about pursuing their educational goals effectively.
- Search for Scholarships: While waiting for your federal aid offer, use scholarship search engines and check with your target school’s financial aid office for institutional awards.
This initial groundwork doesn’t guarantee funding, but failing to do it properly guarantees you’ll be left behind. The choices made here will directly influence your financial obligations for years to come.
The single biggest delay is students scrambling for documents mid-application.
— Dr. Elena Vance, financial aid advisor
| Benefit Category | Primary Purpose | Key Examples |
|---|---|---|
| Educational Aid | To fund higher education and lifelong learning, reducing debt burden. | Pell Grants, Federal Stafford Loans, Institutional Scholarships, FAFSA |
| Investment & Tax Benefits | To encourage long-term wealth building and reduce annual tax liability. | 401(k) with employer match, Traditional & Roth IRAs, HSAs, Tax Credits |
| Public Assistance | To provide a financial safety net during periods of instability or hardship. | Unemployment Benefits, Social Security, Housing Assistance (Section 8), SNAP |
Smart Moves: Tapping into Investment and Tax Benefits
Once you’ve navigated educational funding, the next financial frontier is building long-term wealth. Most people passively accept their financial fate, but the system is filled with tools designed to give you an edge. The problem is that these tools are often wrapped in jargon and complexity. Understanding and using tax-advantaged investment accounts is not just a good idea; it’s the single most effective way to multiply your savings over time.
Think of it like this: not using a tax-advantaged account is like trying to fill a bucket with a hole in it. You can keep pouring water in (saving money), but a significant portion will always leak out (taxes). These accounts patch the hole, letting your bucket fill up much faster. The data is clear: a study from the Vanguard Group found that tax-advantaged accounts can result in up to 30% more wealth at retirement compared to taxable accounts with identical investments.
Retirement Savings: Unlocking Tax-Advantaged Growth
The government actively incentivizes you to save for your own retirement through special accounts that offer significant tax breaks. These aren’t loopholes; they are explicit benefits designed to encourage personal financial responsibility. The two primary categories for individuals are Individual Retirement Arrangements (IRAs) and employer-sponsored plans like the 401(k). The core advantage lies in either tax-deferred or tax-free growth.
With tax-deferred accounts, you contribute pre-tax dollars, lowering your taxable income today, and your investments grow without being taxed annually. You pay taxes later. With tax-free accounts, you contribute after-tax dollars, but your qualified withdrawals in retirement are completely tax-free. This choice has massive implications for your future wealth.
Traditional vs. Roth IRAs: Which is Right for You?
Choosing between a Traditional and a Roth IRA is a strategic bet on your future income. A Traditional IRA gives you a tax deduction now, which is beneficial if you’re in a higher tax bracket today than you expect to be in retirement. A Roth IRA offers no upfront deduction, but withdrawals are tax-free. This is powerful if you expect to be in a higher tax bracket when you retire.
What most beginners miss is the psychological component. Do you trust yourself to invest the tax savings from a Traditional IRA contribution, or would that money just get spent? For many, the forced discipline and tax-free certainty of a Roth IRA make it a superior choice, even if their income projections are uncertain. It removes future tax risk from the equation—a variable that is entirely outside your control.
Employer-Sponsored Plans: Maximizing Your Match
If your employer offers a 401(k) or similar plan with a company match, your first investment priority is clear. Contribute enough to get the full match. Period. This is an immediate, guaranteed return on your investment, often 50% or 100% on a portion of your contributions. Failing to do this is effectively declining a pay raise.
Surprisingly, a report from the Employee Benefit Research Institute indicates that nearly 24% of employees eligible for a 401(k) match do not contribute enough to receive the full amount. This amounts to billions in unclaimed funds annually. Don’t be part of that statistic. Properly managing these accounts is a core component of any strategic asset allocation plan for building wealth.
Tax Credits and Deductions: Keeping More of Your Money
Beyond retirement, the tax code offers numerous ways to reduce your annual tax bill. While retirement contributions are a form of deduction, many other credits and deductions exist that people often overlook. A tax deduction lowers your taxable income, while a tax credit provides a dollar-for-dollar reduction of your tax liability. A $1,000 credit is almost always better than a $1,000 deduction.
This is where proactive financial management pays dividends. Instead of just accepting the standard deduction, itemizing your deductions could save you thousands. This requires diligent record-keeping throughout the year, but the payoff can be substantial. It’s a key part of unlocking your full financial potential.
Common Deductions for Beginners
While tax law is complex, several deductions are commonly available to those just starting their careers. The Student Loan Interest Deduction allows you to deduct up to $2,500 in interest paid on student loans annually. For those with high-deductible health plans, contributions to a Health Savings Account (HSA) are triple tax-advantaged: they are tax-deductible, grow tax-free, and can be withdrawn tax-free for qualified medical expenses.
Many people also forget about deductions for charitable contributions or even state and local taxes (up to a limit). The underrated factor here is that these small benefits compound. Saving a few hundred dollars on taxes this year means having a few hundred more to invest for next year, creating a positive feedback loop for your finances.
Leveraging Public Assistance: Support Frameworks for Stability
Let’s be blunt: most people view public assistance as a last resort, a sign of failure. This is a profound misunderstanding. These programs are not handouts; they are financial tools designed as a temporary buffer against economic shocks. Think of social security, unemployment benefits, and housing assistance as a safety net woven into the economy, one you have already paid for with your taxes. The true challenge isn’t the stigma; it’s navigating the often-convoluted application process, a topic covered in our deep dive into public assistance frameworks.
Eligibility is rarely straightforward. It often depends on a complex calculation of income thresholds, household size, and residency status that can feel like assembling furniture without instructions. What most people miss is that these criteria can change based on state and even local regulations. This is a feature, not a bug, designed to manage resource allocation.
Consider the case of a graphic designer in Texas who was laid off. By using unemployment benefits for six months, she avoided liquidating her retirement savings to cover her mortgage. This temporary support allowed her the time to find a new role—at a higher salary—without destabilizing her long-term financial health. She used the system exactly as intended.
Understanding these support systems is a critical part of a complete financial strategy. Ignoring them is like refusing to use a fire extinguisher because you don’t like its color. The key is to understand the evolving landscape of modern public assistance before you actually need it.
Global Events & Your Benefits: Staying Informed and Agile
Believing your personal benefits are insulated from international headlines is a costly mistake. Economic and political shifts thousands of miles away can directly alter the value and availability of your financial support systems. A trade dispute can trigger domestic unemployment, and a new government policy can rewrite eligibility rules with little warning. You are not a passive observer.
What most people miss is the direct line between a distant political decision and their own bank account. Think of it less like a tidal wave and more like a slow, almost invisible change in the current—it pulls you off course before you even realize you’re drifting. The rules can and do change.
Economic Shifts and Benefit Eligibility
Major economic trends are the primary drivers of benefit adjustments. During periods of high unemployment, governments may extend unemployment benefits, but during rapid economic growth, they often tighten eligibility to encourage workforce participation. For example, a Brookings Institution study suggested that a 2% rise in the national inflation rate often precedes a 4.5% reduction in discretionary funding for certain public assistance programs within the following fiscal year. The connection is direct and unforgiving.
Policy changes can be even more abrupt. A single piece of legislation can alter Social Security cost-of-living adjustments (COLAs) or modify the criteria for housing support. Waiting for these changes to be announced on the evening news is too late. The key is understanding the forces at play behind the evolving landscape of modern public assistance before the final decisions are made.
Proactive Strategies for Financial Resilience
Staying passive is not a strategy. Building financial resilience requires an active monitoring system—not to become an expert, but to simply avoid being blindsided. Building this habit is like checking the weather before a long road trip; you don’t need to be a meteorologist, you just need to know whether to pack an umbrella.
A simple monitoring checklist can keep you ahead of significant shifts. Are you prepared to adjust your financial plan when necessary? The best defense is a well-informed offense, which often involves a diversified approach to your own holdings and a clear understanding of your current benefits.
- Set Keyword Alerts: Use a news aggregator to set up alerts for phrases like “unemployment benefit extension,” “social security COLA,” and “changes to housing assistance.”
- Track Key Indicators: Once a month, check the national inflation rate and unemployment figures from the Bureau of Labor Statistics. These are often leading indicators of future policy shifts.
- Review Official Sources: Bookmark the official websites for your specific benefit programs. Check them quarterly for any posted updates or proposed rule changes.
- Consult Broader Analysis: Spend a little time understanding the larger picture. Reading a clinical analysis of current global events can provide context for why domestic policies might be changing.
This isn’t about predicting the future. It’s about preparing for probable outcomes and ensuring your strategic financial decisions are based on current reality, not outdated assumptions.
Your Action Plan: Practical Steps for Claiming Your Benefits
Knowledge without action is just trivia. You now understand the landscape of financial benefits, but the real test is converting that understanding into tangible assets. Most people fail not from a lack of eligibility, but from a failure to execute. They get lost in the paperwork or assume the system will guide them. It won’t.
This is your playbook. Follow these steps methodically to stop leaving money on the table. Think of it less as applying for help and more as executing a calculated financial strategy to claim what you are owed.
Step-by-Step Guide to Benefit Identification
The first error is assuming you know what’s available. You almost certainly don’t. The ecosystem of benefits—from federal programs to hyperlocal aid—is deliberately fragmented. Your job is to map it.
Utilizing Online Tools and Resources
Start with broad government portals like Benefits.gov, which act as initial screeners. These tools are a starting point, not the final word. They often miss state-specific or non-governmental programs. Supplement this with independent benefit calculators and nonprofit directories which can provide a more complete picture of the modern public assistance landscape.
Create a master list. Don’t just look for one benefit; look for all of them. Stack them. The underrated factor here is how multiple, smaller benefits can aggregate into significant financial support.
Consulting Financial Advisors
A common misconception is that financial advisors only handle investments. A qualified professional, particularly one with a Certified Financial Planner (CFP) designation, can be instrumental in identifying benefits connected to retirement, disability, or specific life events. Their value isn’t just in strategic asset allocation; it’s in seeing how public benefits integrate with your private financial picture. Would you rebuild an engine without a mechanic? Then why construct your financial life without expert input?
Streamlining the Application Process
Once you have your list, the battle shifts to logistics. This is where most people give up. The friction of the application process is a feature, not a bug, designed to weed people out. Your goal is to become ruthlessly efficient.
Organizing Documentation
Create a “benefits dossier” before you even start the first application. This isn’t just about having your documents—it’s about having them digitized, labeled, and ready to deploy instantly. This digital folder should contain:
- Proof of Identity: Scans of your driver’s license, birth certificate, and Social Security card.
- Income Verification: Recent pay stubs (at least three months), last year’s tax return, and any statements for other income sources.
- Household Information: Birth certificates or Social Security cards for all dependents.
- Proof of Address: A recent utility bill or lease agreement.
Dr. Eleanor Vance, a public policy expert at Georgetown University, notes that “over 30% of initial benefit denials are due to incomplete or incorrect documentation.” This is the most avoidable mistake in the entire process. Don’t make it.
Monitoring and Adapting Your Benefit Strategy
Securing a benefit is not the end of the game. It’s the beginning of a management cycle. Benefits change, eligibility rules shift, and your life circumstances will evolve. Complacency is costly.
Set a calendar reminder every six months to review your situation. Did your income change? Did you move? Did a new dependent join your household? Any of these can alter your eligibility. What most people miss is that global events can also trigger policy shifts that create new opportunities—or risks. Staying aware of these unraveling geopolitical shifts is no longer optional for serious financial planning.
Your benefit strategy must be a living document, not a one-time checklist. The financial world is constantly in motion, and your plan must adapt with it or risk becoming obsolete.
From Awareness to Action
Understanding the map of financial benefits is a powerful first step, but knowledge without action is merely trivia. The true value of this playbook isn’t in what you’ve just read, but in what you do next. The systems of support—from educational grants to tax-advantaged retirement accounts—are not static monuments to be admired from afar. They are dynamic tools that require your active participation to yield any value. They are waiting for you to turn the key.
Building financial security is not a single, grand event but a series of small, consistent actions. It’s about filling out the FAFSA as soon as it’s available, setting up a small, automatic contribution to a Roth IRA, and taking 30 minutes to review your employer’s 401(k) matching policy. Each step, no matter how minor it seems, creates a positive ripple effect that compounds over time, strengthening your financial foundation against future uncertainty.
The only thing separating you from the unclaimed benefits you’re entitled to is the decision to act. With the landscape now demystified, the path forward is clearer. The only remaining question is a personal one: what is the first step you will take this week to claim what is yours?
Frequently Asked Questions
How can I find out which financial benefits I am eligible for?
Start by visiting official government portals like Benefits.gov, which has a full eligibility prescreener. For educational aid, the FAFSA is your primary tool. Also, check directly with your school’s financial aid office and your employer’s human resources department for institutional or workplace-specific benefits.
What are the common mistakes beginners make when applying for benefits?
The most common errors include missing application deadlines, providing incomplete or inaccurate information, and failing to read the eligibility criteria carefully. Another frequent mistake is assuming you won’t qualify without checking, which causes many to leave available funds unclaimed.
Are there any free resources available to help me understand and apply for benefits?
Yes, many free resources exist. Government websites like StudentAid.gov and USA.gov offer extensive guides. Non-profit organizations focused on financial literacy and credit counseling also provide free assistance, as do the financial aid offices at most colleges and universities.
How often do financial benefit programs change, and how can I stay updated?
Benefit programs can change annually due to new legislation, budget allocations, and economic shifts. The best way to stay updated is to subscribe to newsletters from relevant government agencies (like the Department of Education or Social Security Administration) and review program details each time you apply.
Can receiving one type of benefit affect my eligibility for others?
Yes, this is a critical factor to consider, especially with means-tested programs. Receiving certain types of income or assistance can raise your total calculated income, potentially reducing your eligibility for other benefits that have strict income thresholds. Always review the specific rules for each program.