Medicare Part D Savings 2026: Reduce Prescription Costs by 20%
Anúncios
Navigating the complexities of healthcare, especially as we age, can be a daunting task. For millions of Americans, Medicare Part D is a critical component of their healthcare coverage, specifically designed to help manage prescription drug costs. As we look towards 2026, significant changes are on the horizon for Medicare Part D, presenting both challenges and unprecedented opportunities for savings. Our goal with this comprehensive guide is to empower you with the knowledge and strategies to unlock substantial savings, potentially reducing your prescription costs by 20% or more.
Anúncios
The landscape of prescription drug coverage under Medicare is constantly evolving, driven by legislative changes, market dynamics, and a continuous effort to make medications more affordable. Understanding these shifts, particularly those slated for 2026, is paramount to making informed decisions about your healthcare and financial well-being. This article will delve deep into the upcoming changes, highlight key strategies for maximizing your Medicare Part D savings, and provide practical advice to ensure you’re getting the most value from your plan.
Understanding the Evolution of Medicare Part D
Medicare Part D, established in 2006, was designed to help Medicare beneficiaries pay for prescription drugs. It’s offered through private insurance companies approved by Medicare, and each plan varies in its costs and the drugs it covers. Over the years, the program has undergone several modifications aimed at improving affordability and accessibility. The changes coming in 2026 are some of the most impactful yet, largely stemming from recent legislative efforts to rein in drug prices and reduce out-of-pocket expenses for seniors.
Anúncios
Key Changes for 2026 Affecting Your Medicare Part D Savings
The most significant change anticipated for 2026 is the implementation of a new annual out-of-pocket cap for prescription drug costs. This cap is a game-changer, as it directly limits how much beneficiaries will have to pay for their medications each year, offering a predictable ceiling on expenses. While the exact figure is subject to adjustment, this cap is expected to provide substantial relief, especially for those with high prescription drug needs.
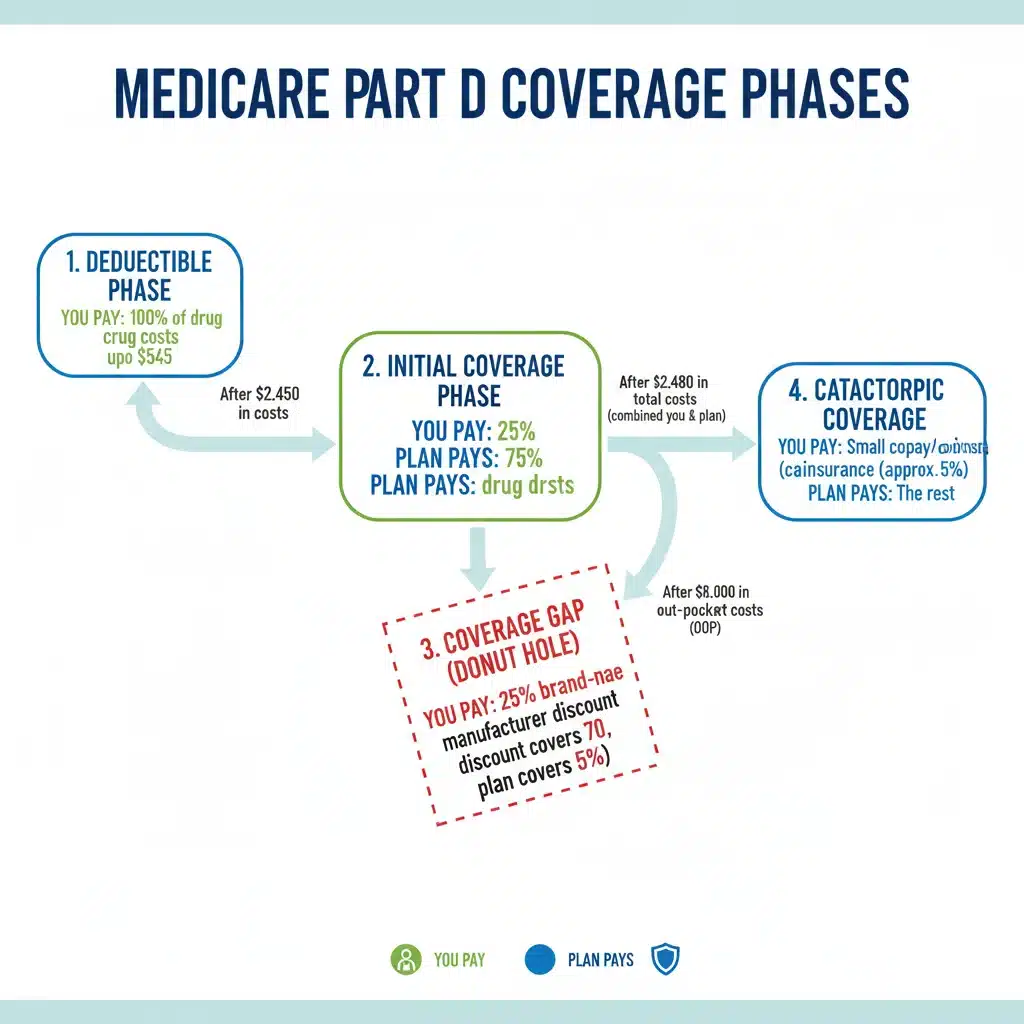
Furthermore, there will be adjustments to the various phases of Part D coverage: the deductible, initial coverage phase, coverage gap (or ‘donut hole’), and catastrophic coverage. These modifications are designed to smooth the transition between phases and ensure that beneficiaries receive more financial assistance earlier in the year. The aim is to reduce the burden of high drug costs and make healthcare more predictable for seniors and individuals with disabilities.
It’s also important to note potential changes in how manufacturers’ discounts and pharmacy price concessions are factored into the overall cost structure. These behind-the-scenes adjustments can significantly influence the premiums and out-of-pocket costs you face, ultimately impacting your overall Medicare Part D savings.
Strategies to Maximize Your Medicare Part D Savings in 2026
With these changes approaching, proactive planning is crucial. Here are actionable strategies you can employ to ensure you maximize your Medicare Part D savings in 2026:
1. Annual Plan Review: A Non-Negotiable Step
Every year, during the Annual Enrollment Period (AEP) from October 15th to December 7th, you have the opportunity to review and switch your Medicare Part D plan. This annual review becomes even more critical with the 2026 changes. Plans can alter their formularies (list of covered drugs), premiums, deductibles, and cost-sharing structures. What was the best plan for you this year might not be next year.
- Check Your Medications: Ensure all your current prescriptions are covered by the plan’s formulary. Pay close attention to any changes in tier placement, as this directly affects your co-pay.
- Compare Premiums and Deductibles: While a lower premium might seem attractive, a higher deductible could negate those savings if you have significant drug costs. Conversely, a higher premium might be worthwhile for a plan with a lower deductible and better overall coverage.
- Analyze Pharmacy Networks: Confirm that your preferred pharmacies are in-network to avoid higher out-of-pocket costs. Some plans offer preferred pharmacy networks with lower co-pays.
- Utilize Medicare’s Plan Finder: The official Medicare.gov Plan Finder tool is an invaluable resource. It allows you to enter your medications and preferred pharmacies to compare plans side-by-side, estimate your annual costs, and identify the most cost-effective option.
2. Understanding the New Out-of-Pocket Cap
The introduction of an annual out-of-pocket cap is a significant benefit. For those with high prescription drug costs, this cap will provide a clear limit on their financial exposure. Understanding how this cap works and its potential impact on your personal finances is vital. Once you reach this cap, you will pay nothing for your covered Part D drugs for the remainder of the year.
This change effectively eliminates the ‘catastrophic coverage’ phase as we know it, where beneficiaries still paid a small percentage of drug costs even after reaching a high spending threshold. The new cap simplifies the structure and provides more robust protection against exorbitant drug expenses. Factor this into your budgeting and plan selection; if you anticipate high drug costs, a plan that helps you reach this cap more efficiently might be beneficial.
3. Exploring Generic and Preferred Brand-Name Drugs
This strategy remains a cornerstone of Medicare Part D savings. Generics are typically significantly cheaper than their brand-name counterparts and are equally effective. Always ask your doctor if a generic alternative is available for your prescriptions. If not, inquire about preferred brand-name drugs on your plan’s formulary, as these often have lower co-pays than non-preferred brands.
- Talk to Your Doctor: Your physician can often prescribe a generic or a therapeutically equivalent preferred brand if available.
- Consult Your Pharmacist: Pharmacists are excellent resources for identifying cost-saving alternatives and understanding your plan’s formulary.
4. Utilizing Patient Assistance Programs and Extra Help
Even with Medicare Part D, some beneficiaries may struggle with prescription costs. Several programs can provide additional financial assistance:
- Extra Help (Low-Income Subsidy): This federal program helps people with limited income and resources pay for their Medicare Part D premiums, deductibles, and co-payments. Eligibility requirements are updated annually, so it’s worth checking if you qualify.
- Pharmaceutical Company Patient Assistance Programs (PAPs): Many pharmaceutical manufacturers offer programs to help uninsured and underinsured patients afford their medications. While primarily designed for those without coverage, some programs may offer assistance to Medicare beneficiaries for specific high-cost drugs.
- State Pharmaceutical Assistance Programs (SPAPs): Some states offer their own programs to help residents with prescription drug costs. Check with your state’s Department of Health or Area Agency on Aging for information on available programs.
- Non-Profit Organizations: Various non-profit organizations offer assistance for specific diseases or general prescription drug costs.
5. Considering Mail-Order Pharmacies and 90-Day Supplies
Many Medicare Part D plans offer incentives for using mail-order pharmacies, often providing a 90-day supply of maintenance medications for a lower co-pay than a 30-day supply at a retail pharmacy. This can lead to substantial Medicare Part D savings over the year, especially for chronic conditions.
- Convenience: Mail-order services deliver directly to your home, saving you trips to the pharmacy.
- Cost Savings: Often, the co-pay for a 90-day supply is less than three separate 30-day co-pays.
The Impact of the Inflation Reduction Act on 2026 Medicare Part D Savings
The changes coming in 2026 are largely a result of the Inflation Reduction Act (IRA) of 2022. This landmark legislation aims to lower prescription drug costs for millions of Americans by allowing Medicare to negotiate drug prices, capping out-of-pocket costs, and penalizing drug companies for excessive price increases. While the full effects of the IRA will unfold over several years, 2026 marks a pivotal point for Part D beneficiaries.
Medicare Drug Price Negotiation
One of the most significant provisions of the IRA is allowing Medicare to negotiate prices for certain high-cost prescription drugs. While the first negotiated prices will take effect in 2026 for a select number of drugs, this mechanism is expected to expand over time, leading to lower costs for both Medicare and beneficiaries. This direct negotiation power is projected to create substantial Medicare Part D savings in the long run.
Redesign of the Part D Benefit
The IRA also fundamentally redesigns the Medicare Part D benefit structure. Beyond the out-of-pocket cap, it shifts more financial responsibility onto drug manufacturers and plans in the catastrophic phase, reducing the government’s (and thus taxpayers’) share. This redesign is intended to incentivize plans and manufacturers to manage drug costs more effectively, which could indirectly lead to lower premiums and better overall value for beneficiaries.
Navigating the Annual Enrollment Period (AEP) for 2026
As 2026 approaches, the AEP will be your prime opportunity to adapt to the new Part D landscape. Here’s how to make the most of it:
- Start Early: Don’t wait until the last minute. Begin researching plans in early October.
- Gather Your Information: Have a list of all your current medications, including dosages and frequency, as well as your preferred pharmacies.
- Use Official Resources: Rely on Medicare.gov, your State Health Insurance Assistance Program (SHIP), or trusted Medicare brokers for accurate and unbiased information.
- Seek Personalized Advice: If you find the options overwhelming, consider consulting with a licensed Medicare agent or a SHIP counselor. They can provide personalized guidance based on your specific health needs and financial situation.
Common Pitfalls to Avoid When Choosing a Medicare Part D Plan
While the goal is to maximize your Medicare Part D savings, it’s equally important to avoid common mistakes that can lead to higher costs or inadequate coverage:
- Ignoring the Formulary: Choosing a plan without verifying if your drugs are covered can lead to significant out-of-pocket expenses for non-formulary medications.
- Focusing Only on Premiums: A low premium might mask high deductibles or co-pays, especially for expensive drugs. Always consider the total estimated annual cost.
- Not Reviewing Annually: Plans change, and so do your health needs. Sticking with the same plan year after year without review is a common reason for overpaying.
- Misunderstanding the ‘Donut Hole’ (Coverage Gap): While the 2026 changes significantly alter the coverage gap, understanding its current and future impact on your costs is crucial during the transition. The out-of-pocket cap effectively closes the ‘donut hole’ for beneficiaries by limiting their spending, but the mechanics leading up to that cap still involve different cost-sharing responsibilities.
- Falling for Scams: Be wary of unsolicited calls or emails promising too-good-to-be-true Medicare deals. Always verify information with official Medicare sources.
Case Study: Potential 20% Savings in Action
Let’s consider a hypothetical scenario to illustrate how Medicare Part D savings could reach 20% or more for a beneficiary in 2026. Mrs. Rodriguez, a senior with several chronic conditions, currently pays approximately $5,000 annually in out-of-pocket costs for her prescription medications, including premiums, deductibles, and co-pays. This amount places her well into the current ‘donut hole’ phase and close to catastrophic coverage.
Under the 2026 changes, with the new out-of-pocket cap, let’s assume the cap is set at $2,000 (the exact number will be announced closer to 2026). If Mrs. Rodriguez optimizes her plan choice, selecting a plan with a favorable formulary and low co-pays for her specific drugs, her annual out-of-pocket spending would be capped at $2,000. This represents a direct saving of $3,000 compared to her previous $5,000, which is a 60% reduction in her out-of-pocket costs!
Even for someone with more moderate drug costs, say $2,000 annually, strategic plan selection, utilizing generics, and potentially mail-order options could reduce their spending to $1,600 or less, achieving that 20% saving target. For example, if a beneficiary switches from a brand-name drug with a $50 co-pay to a generic with a $10 co-pay for a medication taken monthly, that’s an annual saving of $480 on just one drug. Multiply this across several medications, and the savings quickly add up.
The key takeaway from this case study is that the 2026 changes, combined with diligent plan selection and utilization of available resources, present a significant opportunity for all beneficiaries to achieve substantial Medicare Part D savings.
Looking Ahead: Preparing for 2026 and Beyond
The journey to maximizing your Medicare Part D savings doesn’t end in 2026. The healthcare landscape is dynamic, and continuous engagement with your coverage is essential. Stay informed about future legislative changes, plan updates, and new drug developments. Regularly review your medication list with your doctor to ensure you’re on the most effective and cost-efficient treatments.
Medicare Part D is a vital program that provides access to necessary medications. By understanding the upcoming changes, actively reviewing your plan options, and utilizing all available resources, you can confidently navigate 2026 and beyond, ensuring your prescription drug costs are as manageable as possible.
Conclusion
The year 2026 marks a significant turning point for Medicare Part D beneficiaries, ushering in changes designed to provide greater financial protection and predictability for prescription drug costs. The introduction of an annual out-of-pocket cap, coupled with a redesigned benefit structure, offers an unprecedented opportunity to achieve substantial Medicare Part D savings.
By diligently reviewing your plan during the Annual Enrollment Period, embracing generic alternatives, exploring patient assistance programs, and leveraging mail-order pharmacies, you can strategically position yourself to reduce your prescription costs by 20% or even more. Empower yourself with knowledge, take proactive steps, and secure your financial well-being in the evolving Medicare landscape. Your health and your wallet will thank you.